

On Monday morning, November 2, the Michigan Department of Treasury sent out a short bulletin. It was the kind of notice that usually lands in inboxes, gets skimmed, and disappears. This one was different. It marked ten years of MiABLE, Michigan’s savings program for people with disabilities, and it carried a message that still has not reached the people who need it most: you can save money without losing the benefits that keep you alive.
That sounds simple. It is not. For decades, the rule for people on Supplemental Security Income was brutal and clear. Save more than $2,000, and you lose your check. Save more than $2,000, and you lose Medicaid. So people did what the system taught them to do. They spent down. They hid cash. They turned down work. They stayed poor on purpose, because the alternative was worse.
The Argument
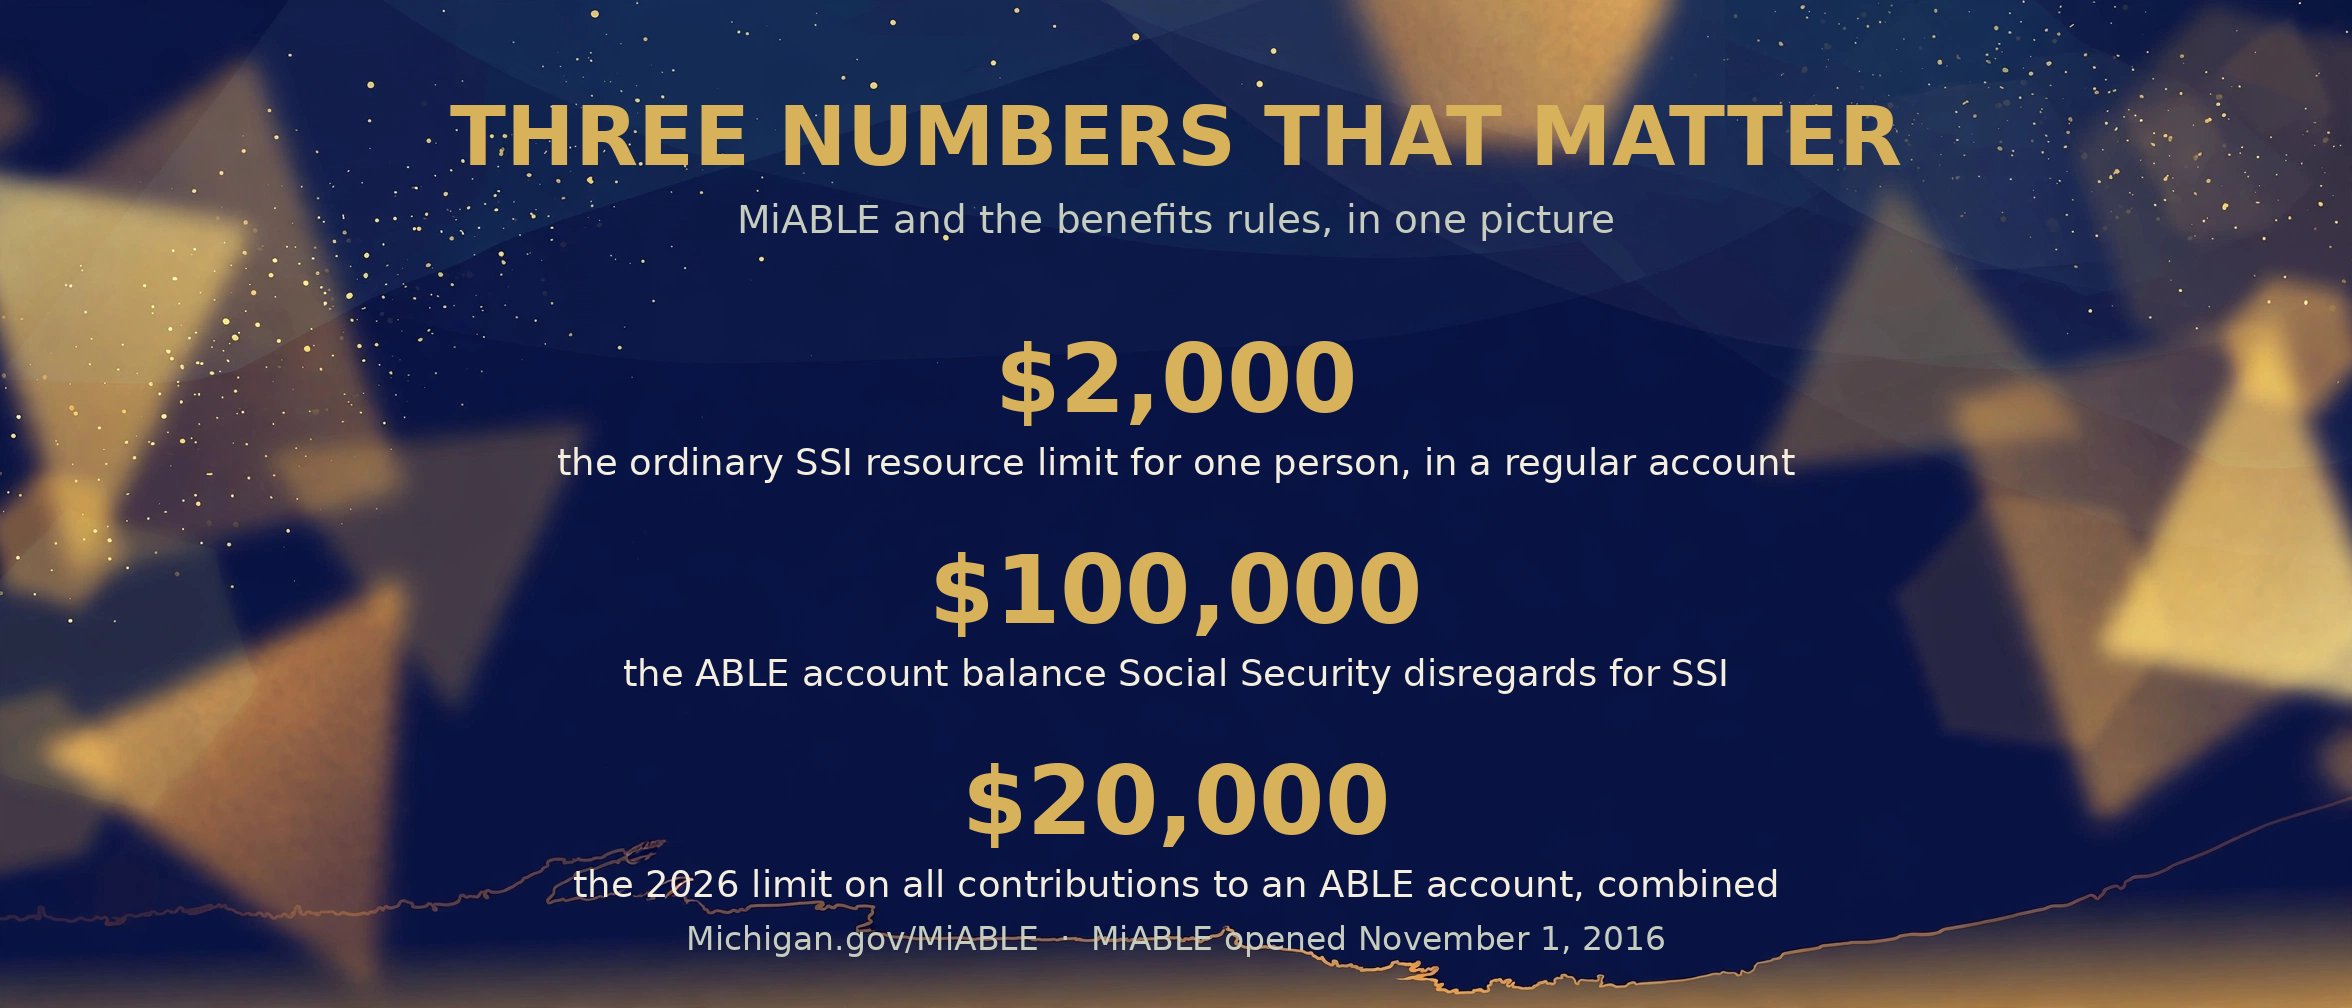
MiABLE was supposed to break that trap. It is Michigan’s version of the federal ABLE Act, passed in 2014 and launched here in 2016. The idea is straightforward: a person with a disability that began before age 46 can open an account, save up to $100,000, and not have that money count against SSI. The first $100,000 is exempt. After that, SSI cash payments pause, but Medicaid continues. It is, on paper, the rare government program that rewards saving instead of punishing it.
The problem is not the law. It is the knowledge. Ten years in, caseworkers still give wrong answers. Families still hear that any savings will kill benefits. People still turn down jobs, refuse inheritances, and drain accounts before a review, because no one told them the rules changed. The bulletin from Treasury was a reminder. It was also an admission: the program works, but the message has not.
What Doesn’t Count
Here are the rules, plainly, as they stand in Michigan in 2026:
SSI: The first $100,000 in a MiABLE account does not count toward SSI’s $2,000 resource limit. If the balance goes above $100,000, SSI cash payments are suspended, but Medicaid eligibility continues.
Medicaid: MiABLE balances do not count as a resource for Medicaid in Michigan, regardless of amount, as long as the account is in good standing.
SNAP: MiABLE funds are excluded from SNAP asset tests in Michigan.
HUD housing: MiABLE balances are excluded from HUD’s asset calculations for housing assistance.
Work: Earnings can go into a MiABLE account, and the account itself does not create a new earnings limit. SSI’s existing work rules still apply to income, but savings in MiABLE do not count against the resource test.
That last point matters most. The fear that saving will trigger a review, a cutoff, or a clawback is what keeps balances low. The law says otherwise, for the first $100,000, and for Medicaid, beyond it.
The Numbers
Ten years is a long time for a program to stay a secret. Nationally, ABLE accounts hold more than $2 billion, but only a fraction of eligible people have one. In Michigan, the Treasury bulletin did not give a new enrollment total, but the pattern is familiar: awareness lags behind eligibility, especially in smaller cities and rural counties where caseworkers carry large caseloads and training is thin.
What Happens If You Don’t Know
The cost of not knowing is not abstract. A parent who leaves $5,000 to a child on SSI without a MiABLE account or a special needs trust can trigger a loss of benefits. A worker who saves $3,000 for a car repair can lose Medicaid. A young adult who takes a part-time job and banks the pay can find the account itself becomes the problem. MiABLE does not solve every case, but it solves the most common one: a person who wants to save a little, for a lot of reasons, without starting over.
Why Now
The tenth anniversary matters because the next change is already coming. The federal age limit for ABLE eligibility rises to 46 in 2026, opening the program to more adults whose disabilities began later in life. That expansion only helps if people know the program exists, and if the workers who advise them know the new limit. A bulletin is a start. Training, outreach, and plain-language guides are the rest.
What It Doesn’t Fix
MiABLE does not fix the $2,000 SSI limit for other savings. It does not fix the fear that a review will go wrong. It does not fix the paperwork, the wait times, or the fact that many people still need a trust for larger inheritances. What it does is narrower and more important: it gives a person a place to save, legally, without starting the clock on losing everything else. After ten years, that should not be a secret.
The work is simple, and the payoff is plain: a worker who understands the exemption, a family that doesn’t have to choose between a future and a check, and a program that finally does what it was built to do. MiABLE isn’t a loophole. It’s a promise, and after ten years, it’s time to keep it.
Want Jackson’s top local stories in one place? Browse the businesses shaping the area in the NeighborClick Local directory — JOIN the FREE Private Insider List for local stories, business spotlights, community updates and even if you don’t have business you’ll be an Insider.


Comments